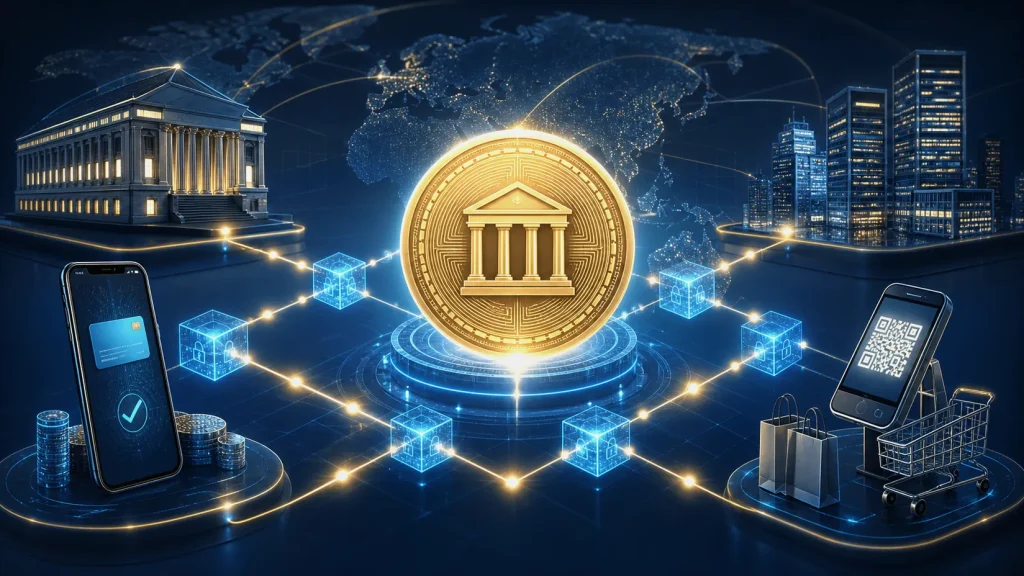
Central Bank Digital Currencies (CBDCs) and Blockchain are moving from policy papers and small pilots into a serious discussion about how everyday money could work. A CBDC is a digital form of a country’s sovereign currency, issued or backed by its central bank. Unlike volatile crypto assets, it is designed to have the same value as physical cash and commercial-bank money—for example, one digital dollar would equal one dollar.

- 50% trading fee discount
- 20% fee cashback
- $6,200 futures bonus

- 20% fee cashback
- $8,000 bonus

- 20% fee cashback
- $60,000 futures bonus

- 20% trading fee discount
- $100 signup bonus
- $10,000 futures bonus

- 20% fee cashback
- $10,000 bonus

- 20% trading fee discount
- $30,050 signup bonus
The important question is not simply whether cash becomes digital. Payments are already heavily digital. The real question is whether a CBDC blockchain system can make settlement faster, improve access to financial services, and preserve trust without creating unnecessary surveillance or disruption to banks.
What makes a CBDC different from cryptocurrency?
Cryptocurrencies such as Bitcoin are generally decentralized networks with independently determined market prices. CBDCs are different in both governance and purpose. They are controlled by a monetary authority, denominated in national currency, and intended to support public payment infrastructure rather than speculation.
A retail CBDC would be available to consumers and businesses for day-to-day payments. A wholesale CBDC would be restricted to banks and approved financial institutions, helping them settle large-value transactions and securities transfers. Many central banks are studying both models because the operational and policy trade-offs are very different.
| Feature | CBDC | Typical cryptocurrency |
|---|---|---|
| Issuer | Central bank | Decentralized protocol or private issuer |
| Value | Tied to national currency | Market-driven, often volatile |
| Governance | Regulated and permissioned | Varies by network |
| Main purpose | Payments and settlement | Trading, payments, applications, or store of value |
How blockchain technology fits into CBDCs
Blockchain is not automatically required for a digital currency. A central bank can use a conventional centralized database, a distributed ledger, or a hybrid architecture. That distinction matters: Central Bank Digital Currencies and Blockchain are related, but they are not interchangeable ideas.
In a permissioned blockchain or distributed ledger, only authorized participants can validate transactions. This may allow banks, payment providers, and the central bank to share synchronized records while maintaining defined access rights. A well-designed ledger can reduce reconciliation work, provide clearer audit trails, and enable near-real-time settlement.
However, blockchain does not magically solve every payments problem. Central banks must evaluate throughput, resilience, energy use, privacy, legal finality, offline payments, and cyberattack exposure. A national payments network cannot afford prolonged downtime or unclear responsibility when a transaction fails. For that reason, many CBDC blockchain technology experiments focus on controlled pilots rather than public, permissionless chains.
Potential benefits of a CBDC blockchain system
A carefully designed CBDC could improve the movement of money in several practical ways:
- Faster settlement: Payments and asset transfers could settle more quickly, including outside standard banking hours.
- Lower friction: Shared infrastructure may reduce the cost and complexity of reconciling records across institutions.
- Financial inclusion: People with limited access to bank branches may gain a secure digital payment option, provided access works on simple devices and supports offline use.
- Programmable payments: Conditional transfers, such as targeted benefits or automated delivery-versus-payment settlement, could be built with strict policy controls.
- Cross-border innovation: Interoperable systems may eventually reduce delays and fees in international payments.
Programmability deserves special care. It can make business processes more efficient, but money should not become an inflexible tool that limits legitimate choices. Any rules should be transparent, lawful, and proportionate to the use case.
Privacy, control, and the biggest policy debate
The most sensitive CBDC issue is privacy. Cash offers a high degree of anonymity. Digital payments, by contrast, typically generate data. If a CBDC is widely adopted, people will reasonably ask who can see their transactions, how long information is retained, and whether data can be misused.
A credible design could use tiered identity checks, privacy-enhancing cryptography, transaction limits for lower-risk payments, and independent oversight. It should also clearly separate routine payment data from law-enforcement access governed by due process. Strong security without meaningful privacy safeguards can weaken public trust, even if the technology performs well.
Another concern is bank disintermediation. If households move large deposits from commercial banks into a central-bank wallet, banks could lose a stable funding source for lending. Policymakers may respond with balance caps, non-interest-bearing retail CBDCs, or a two-tier model in which banks and licensed payment firms manage customer-facing wallets.
CBDCs, stablecoins, and the wider crypto market
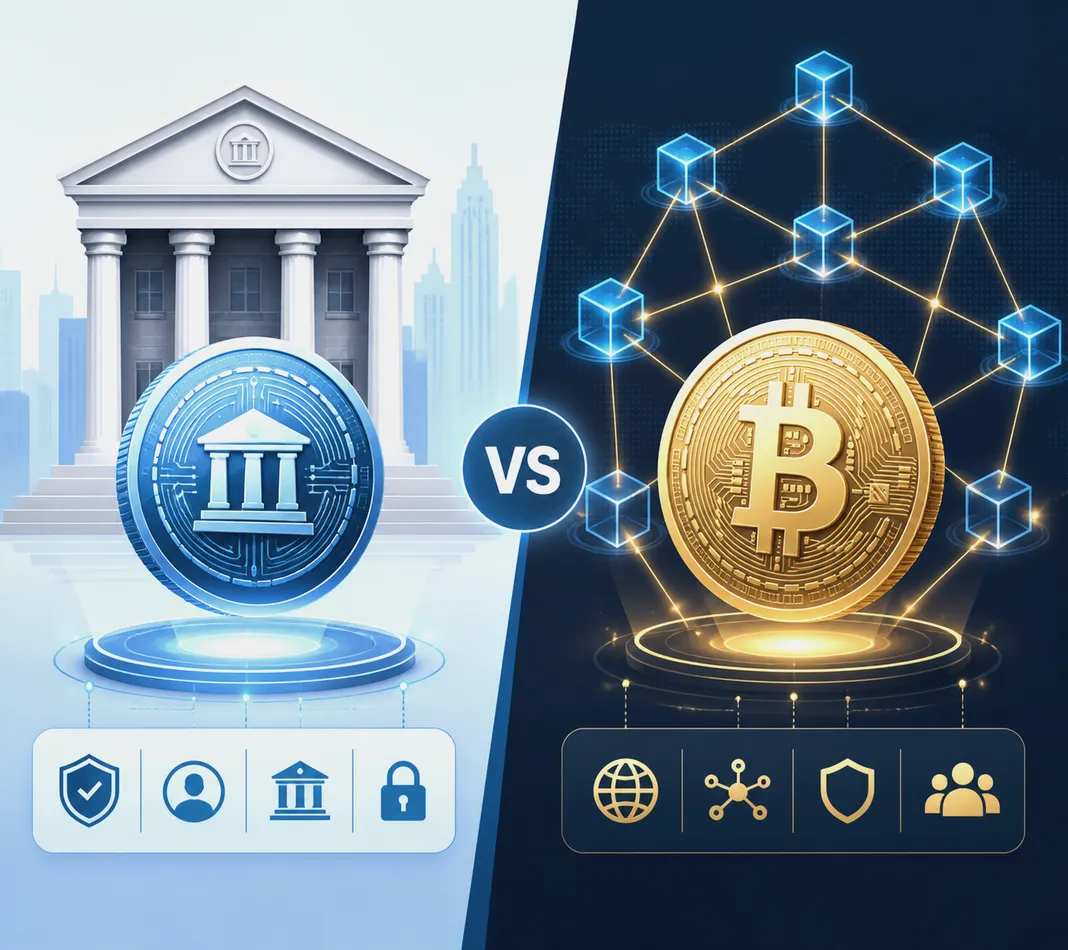
CBDCs may coexist with stablecoins, bank deposits, and decentralized crypto networks rather than replacing them all. Stablecoins can offer speed and global reach, but users must assess reserve quality, issuer risk, redemption rules, and regulation. CBDCs may offer direct sovereign backing, while open blockchain assets continue to serve separate roles in investment, decentralized finance, and network settlement.
For readers who want to follow the broader market while learning about digital currency infrastructure, it is worth choosing platforms carefully and understanding risk before trading. Join Binance with referral code CRYPTONEWER for a 20% fee discount and up to $10,000 in benefits. The offer is promotional, and cryptocurrency prices can move sharply, so research assets and local rules independently before making a decision.
What to watch next in global CBDC development
The future of Central Bank Digital Currencies (CBDCs) and Blockchain will be shaped less by marketing claims than by real-world implementation. Watch for pilot results involving offline functionality, merchant acceptance, interoperability with existing banks, transparent privacy rules, and public consultation. Wholesale projects may reach practical adoption first because they operate among a smaller number of regulated institutions and can target clear settlement inefficiencies.
For consumers, the key benchmark is simple: does a digital currency make payments safer, easier, and more accessible without sacrificing choice or privacy? For businesses, the priorities are reliable settlement, manageable compliance, low integration costs, and compatibility with the payment methods customers already use. Those standards will determine whether CBDCs become a routine layer of financial infrastructure or remain limited tools for specialized use cases.