Government Regulations on Blockchain Technology are rapidly shaping how crypto exchanges, Web3 builders, investors, and traditional companies use decentralized networks. Blockchain itself is simply a distributed record-keeping technology, but the assets, identities, payments, and contracts built on it can trigger laws covering finance, privacy, tax, consumer protection, and sanctions.

- 20% trading fee discount
- $30,050 signup bonus

- 20% trading fee discount
- $100 signup bonus
- $10,000 futures bonus

- 20% fee cashback
- $10,000 bonus

- 20% fee cashback
- $8,000 bonus

- 20% fee cashback
- $60,000 futures bonus

- 50% trading fee discount
- 20% fee cashback
- $6,200 futures bonus
For anyone working with digital assets, the practical question is no longer whether regulation matters. It is which rules apply, where they apply, and what evidence of compliance must be retained.
Why blockchain regulation is complicated
A public blockchain can be global from the first block: a wallet in one country may interact with a protocol developed in another and a liquidity provider located elsewhere. Governments, however, enforce rules through national and regional legal systems. This mismatch creates a patchwork of blockchain regulation rather than one universal rulebook.
Authorities also regulate activities differently. Operating a crypto exchange, issuing a token, holding customer assets, offering a stablecoin, and selling blockchain analytics services do not carry the same legal risk. A token may be treated as a payment instrument in one jurisdiction, a security in another, or something that needs a case-by-case assessment.
The main categories of government regulations on blockchain technology
Anti-money laundering and identity controls
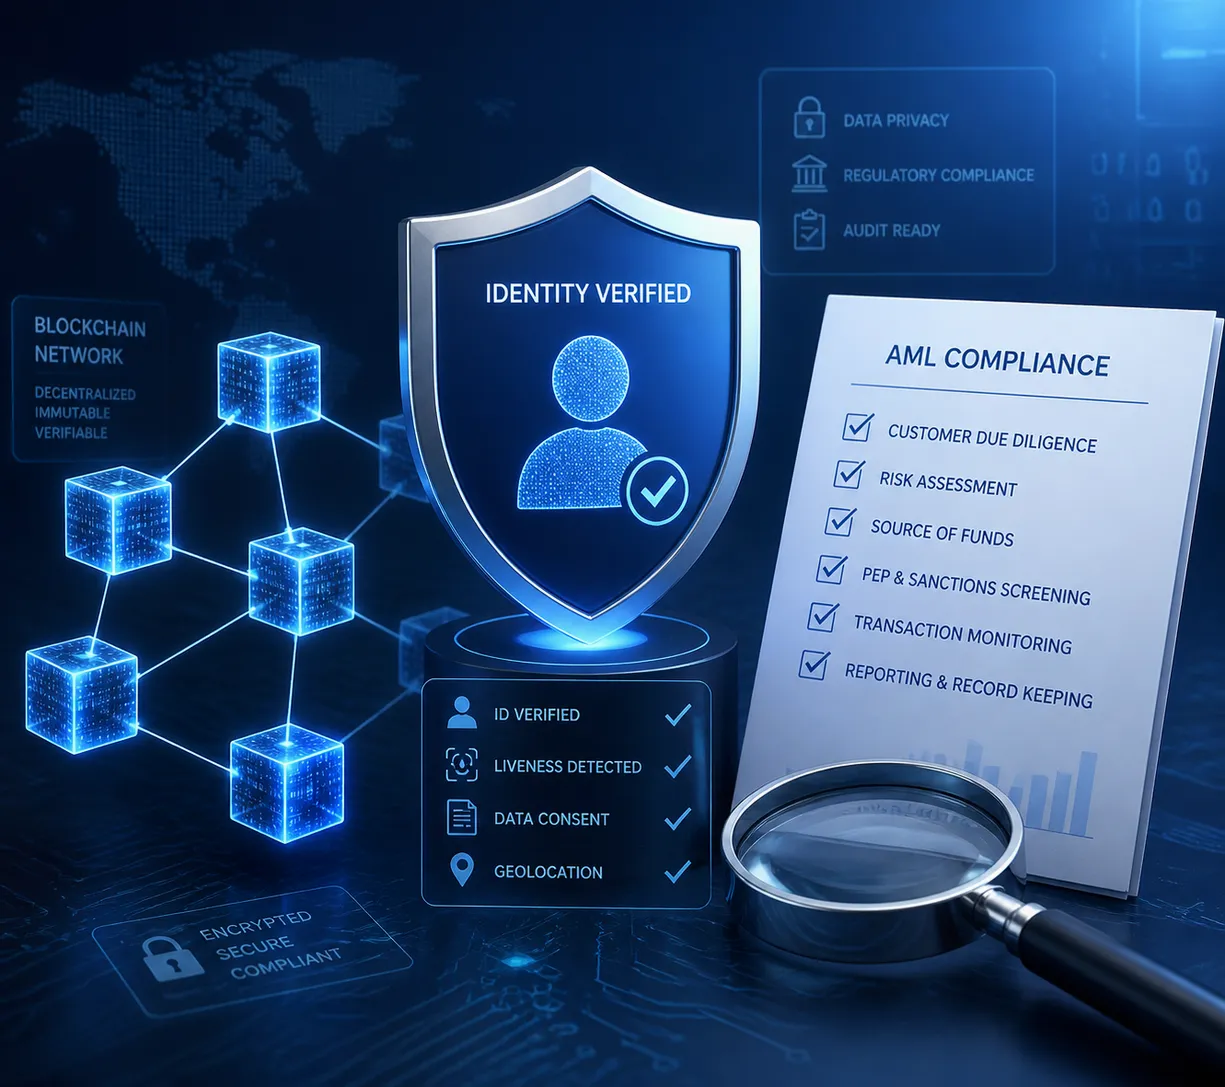
The most widespread cryptocurrency compliance requirement involves anti-money laundering (AML) and know-your-customer (KYC) controls. Regulated virtual asset providers are generally expected to verify customers, monitor suspicious activity, keep records, and report qualifying transactions to relevant authorities.
These obligations explain why reputable centralized platforms request identity documentation and may ask for the source of funds. This is not merely an exchange preference; it can be central to meeting AML, counter-terrorist-financing, and sanctions-screening obligations.
If you want a platform that provides an on-ramp to digital assets, consider registering with Binance using referral code CRYPTONEWER. The promotion advertises a 20% trading-fee discount and up to $10,000 in benefits; always review eligibility, local availability, and the platform terms before relying on a promotion.
Securities and token issuance rules
One of the hardest areas of blockchain law is deciding whether a digital token is a security or another regulated financial product. Regulators often examine the economic reality of an offering rather than its label. Marketing that emphasizes profit, promises of managerial effort, revenue sharing, or investor-like rights can raise the stakes considerably.
For founders, this means a white paper is not a substitute for legal analysis. Token distribution mechanics, geographic restrictions, disclosures, vesting, secondary-market trading, and promotional language all deserve careful review. The long-tail issue how to comply with blockchain token regulations starts with understanding what is actually being offered.
Stablecoin and payment regulation
Stablecoins have drawn strong attention because they aim to function as a medium of exchange or store of value. Depending on the jurisdiction, an issuer may face reserve, redemption, governance, audit, safeguarding, licensing, and disclosure requirements. Payment-focused rules can apply even when the underlying technology is decentralized.
Users should examine how a stablecoin maintains its peg, where reserves are held, whether redemptions are available, and what legal entity is responsible. Terms such as “fully backed” should be verified through credible, current documentation rather than accepted as marketing language.
Privacy, data protection, and immutable records
Blockchain’s permanence can conflict with data-protection principles. Personal data written directly to an immutable ledger may be difficult—or impossible—to amend or erase. Businesses should avoid placing unnecessary identifiable information on-chain and should assess whether hashes, metadata, wallet histories, or linked records can identify a person.
A sensible design approach is to keep sensitive data off-chain, record only what is necessary on-chain, use access controls where appropriate, and document the purpose and retention of data. Privacy engineering is increasingly a compliance requirement, not an optional feature.
Tax reporting and record retention
Tax authorities in many locations treat crypto transactions as reportable events. Trading one asset for another, receiving staking rewards, earning tokens for work, selling NFTs, and using digital assets to pay for goods may all have tax consequences. The exact treatment varies, but incomplete records are a universal problem.
Keep timestamps, transaction IDs, wallet addresses, fair-market-value calculations, fees, and records of transfers between wallets you control. Good records make it easier to distinguish a taxable disposal from a simple transfer and help support filings if questions arise later.
Global blockchain laws: jurisdiction still matters
The phrase global blockchain laws can be misleading because businesses must map each relevant connection: where the company is incorporated, where its team operates, where customers live, where it markets services, and where financial partners are located. A website being accessible in a country does not always create an obligation, but actively targeting residents often changes the analysis.
The European Union has developed a structured market framework for certain crypto-assets, while the United States relies heavily on a combination of federal and state agencies, existing financial rules, and enforcement actions. Other countries may use licensing regimes, sandboxes, restricted access models, or outright limits on certain crypto activities. Rules evolve, so legal advice and official regulator guidance should be checked before a launch or major product change.
A working compliance checklist for blockchain businesses
A practical blockchain compliance program should be proportional to the service offered, but it commonly includes:
- Classifying the product: Document whether the project involves custody, exchange, payments, token issuance, lending, or software-only services.
- Mapping jurisdictions: Identify customer locations, operating entities, service providers, and marketing territories.
- Building AML controls: Establish KYC, sanctions screening, risk scoring, monitoring, escalation, and recordkeeping processes when required.
- Writing transparent disclosures: Explain technology risks, fees, custody arrangements, token rights, conflicts, and limitations in plain language.
- Securing smart contracts: Use independent reviews, test incident procedures, manage administrative keys carefully, and disclose upgradeability.
- Managing consumer complaints: Provide clear support channels, transaction information, and an internal process for resolving disputes.
- Reviewing promotions: Ensure affiliate claims, token advertisements, yield statements, and referral offers are accurate and properly qualified.
What individual users can do now
Individuals do not need to become lawyers to use blockchain responsibly. Start by using services available in your jurisdiction, completing required verification honestly, saving transaction records, and reading the risks attached to tokens and DeFi protocols. Be especially skeptical of products claiming guaranteed returns, anonymous “no questions asked” cash-outs, or effortless tax avoidance.
For traders, exchange compliance can also affect everyday account use. Verify account ownership details, secure the account with strong authentication, understand withdrawal procedures, and check whether a product is offered in your region. You can explore Binance’s registration offer with code CRYPTONEWER for the stated 20% fee discount and potential $10,000 benefits, subject to the applicable terms and local rules.
Regulatory trends worth monitoring
The next phase of Government Regulations on Blockchain Technology is likely to focus on clearer licensing boundaries, stablecoin reserve standards, enhanced reporting, cross-border information sharing, and accountability for intermediaries. At the same time, policymakers must balance fraud prevention with room for open-source development and legitimate innovation.
For builders and users alike, the strongest strategy is not to treat compliance as a barrier added at the end. Make it part of product design: minimize sensitive data, communicate risks honestly, preserve reliable records, and revisit the legal analysis whenever a protocol, token, or customer base changes.